First-Time Home Buyer in Dallas–Fort Worth: The Whole Process, From Preapproval to Keys
Start with a 15-minute call and a real preapproval before you tour a single house. Then compare the loans you actually qualify for: VA or USDA with $0 down if you are eligible, FHA at 3.5%, or conventional at 3% (or 1% with lender-paid help for income-qualified buyers). Add Texas down payment assistance and the real property tax for the address. Most loans close in about 21 to 30 days after your offer is accepted.
Key takeaways
- Preapproval comes first. It verifies your income, assets and credit, so sellers take your offer seriously.
- Down payment can be $0 to 3.5% depending on the program: VA and USDA $0 for eligible buyers, FHA 3.5%, some conventional 3%, or 1% with lender-paid assistance.
- Texas help exists: TSAHC Homes for Texas Heroes, TDHCA My First Texas Home, plus some city and lender programs.
- Property tax is the big Texas line, about 2% of value a year or more in many DFW cities. File your homestead exemption after you move in.
- One person from first call to keys: I shop multiple lenders and send you and your agent a weekly update until clear to close.
Is it hard to buy your first house in DFW?
It is not hard when you do the steps in the right order. Most of the stress I see comes from doing them backward: touring homes on a weekend in Celina or Lewisville, falling for one, and then finding out what the loan, the taxes and the cash to close really look like.
I have closed loans for a lot of first-time buyers: teachers, young families, a retired school teacher, and my own baby brother here in Dallas. The ones who feel calm on closing day all did the same thing. They got the numbers first and shopped second.
Here is the order I walk my clients through:
- Talk it through. A 15-minute call about your goals, timeline and budget. No credit pull.
- Get preapproved. Apply online in about ten minutes. I verify income, assets and credit, compare lenders and programs, and send a preapproval you can shop with.
- Pick the loan. We line up the programs you qualify for side by side.
- Check down payment help. Texas and lender programs can cover part or all of it for eligible buyers.
- Shop and make an offer with your agent, using the real tax rate for each address.
- Underwriting and appraisal. I keep you, your agent and the title company updated every week.
- Close and get the keys. Most loans take about 21 to 30 days from contract.
Where do I start if I have never bought a home?
Start with a budget you can live with in a normal month, not the biggest number a bank will approve. Think about the full payment: principal and interest, property taxes, homeowners insurance, mortgage insurance if your loan has it, and HOA dues if the neighborhood has them. Then decide how much savings you want left in the bank after closing.
Bring both numbers to our first call. If you and your spouse are buying together in Mansfield, bring both of your questions. Couples often have different worries: one is thinking about the payment, the other about the savings account. We cover both. If you are self-employed, tell me how you are paid; my self-employed mortgage guide for DFW lists what lenders will ask for.
Pre-qualification or preapproval?
A pre-qualification is a quick estimate. A preapproval verifies your income, assets and credit before the letter goes out, so your offer is not built on a guess. I recommend preapproval before you tour homes. In places like Plano, where corporate moves around Legacy put buyers on tight timelines, a solid preapproval is what lets you make an offer the same week. My step-by-step guide to mortgage preapproval in DFW shows what to gather.
When you are ready, you can start your application online. If you would rather talk first, that is how most of my first-time buyers begin.
What mortgage is best for a first-time buyer?
The best mortgage is the one that fits your eligibility, your savings and the home you want. A buyer in North Richland Hills with VA eligibility and a buyer in Arlington rebuilding credit should not get the same answer. Here is how the main options compare.
What the table shows
| Loan | Down payment from | Mortgage insurance | Often fits |
|---|---|---|---|
| VA | $0 for eligible borrowers | No monthly PMI; one-time funding fee (can be financed, usually waived with a service-connected disability rating) | Veterans, active duty, Guard and Reserve, eligible surviving spouses |
| USDA | $0 | Upfront guarantee fee and a small annual fee | Homes in eligible rural and suburban areas, household income under the area limit |
| FHA | 3.5% | Upfront and annual MIP; with less than 10% down it usually stays for the life of the loan | Buyers rebuilding credit or with limited savings; gift funds allowed |
| Conventional | 3% on some programs | PMI under 20% down, removable once you reach enough equity | Buyers with steadier credit who want PMI to go away later |
| Conventional with lender-paid assistance | 1% from you | Depends on the program | Income-qualified buyers who are short on savings |
How to read it: the down payment is only one column. Mortgage insurance and the fees in the third column change the monthly payment for years, so I price every option you qualify for on the same house before you choose. Programs and terms vary by lender and change over time; I quote them for your file.
VA loans
If you served, start here. VA loans offer $0 down for eligible borrowers, no monthly mortgage insurance and limits on closing costs. I can pull your Certificate of Eligibility for you in most cases. Fort Worth buyers near NAS JRB use this one a lot.
USDA loans
USDA loans are $0 down in eligible areas, which are often closer to the city than people think. If you are a first-time buyer in Denton looking at outlying addresses, send me the address and I will check the USDA eligibility map. Your household income also has to be under the area limit.
FHA loans
FHA loans need 3.5% down and allow more flexible credit and income guidelines. Many lenders look for a 620 score or higher, and FHA allows lower scores with a larger down payment. The home also has to meet FHA property standards, and loan amounts are capped by county.
Conventional loans: 3% and 1% down
A conventional 30-year fixed mortgage gives you the lowest monthly payment of the fixed terms and a rate that never changes. Some conventional programs start at 3% down, and for income-qualified buyers some lenders offer 1% down with lender-paid assistance. One of my clients, a retired school teacher in Kansas City, bought with just 1% down and ended up paying less than rent.
If the payment has room, a 15-year fixed pays the home off in half the time. If the house needs work, an FHA 203(k) renovation loan finances the purchase and the repairs in one mortgage. You can compare all loan options on one page.
Not sure which of these you qualify for? Fifteen minutes on the phone usually settles it, with no credit pull.
Book 15 minutes with CraigCan Texas down payment assistance help a first-time buyer?
Yes, if you meet the program rules. Down payment assistance can cover part or all of your down payment and sometimes closing costs. I check it early, before you make an offer, so you know your real cash to close.
- TSAHC Homes for Texas Heroes is a statewide program from the Texas State Affordable Housing Corporation for eligible professions, such as teachers, first responders and veterans.
- TDHCA My First Texas Home is a statewide program from the Texas Department of Housing and Community Affairs for eligible first-time buyers and veterans.
- City and lender programs. Some cities and some of the lenders I work with have their own help.
Income limits, price limits and terms are set by each program and change, so I confirm them for your file instead of guessing. Ask three questions about any assistance: is it a grant or a second loan, what happens if you sell or refinance early, and does it change your rate?
Here is what it can look like. A first-time buyer in Prairie View, Texas, used a program from one of my lenders that covered both the down payment and the closing costs, with money left over to buy down the rate.
What does buying your first home cost?
Think of the cash in three stages: what you pay soon after your offer is accepted, what you bring to closing, and what you pay every month after that.
- After the offer: earnest money and, on most Texas contracts, an option fee, plus the home inspection.
- During the loan: the appraisal and any fees due before closing.
- At closing: your down payment, lender and title charges, prepaid items and the first deposit into your escrow account, minus any seller or lender credits.
- Every month: principal and interest, property taxes, homeowners insurance, mortgage insurance if your loan has it, and HOA dues.
Exact fees vary by lender and program, and I quote them for your file. The document that shows them is the Loan Estimate. A lender must send it within three business days of your application.
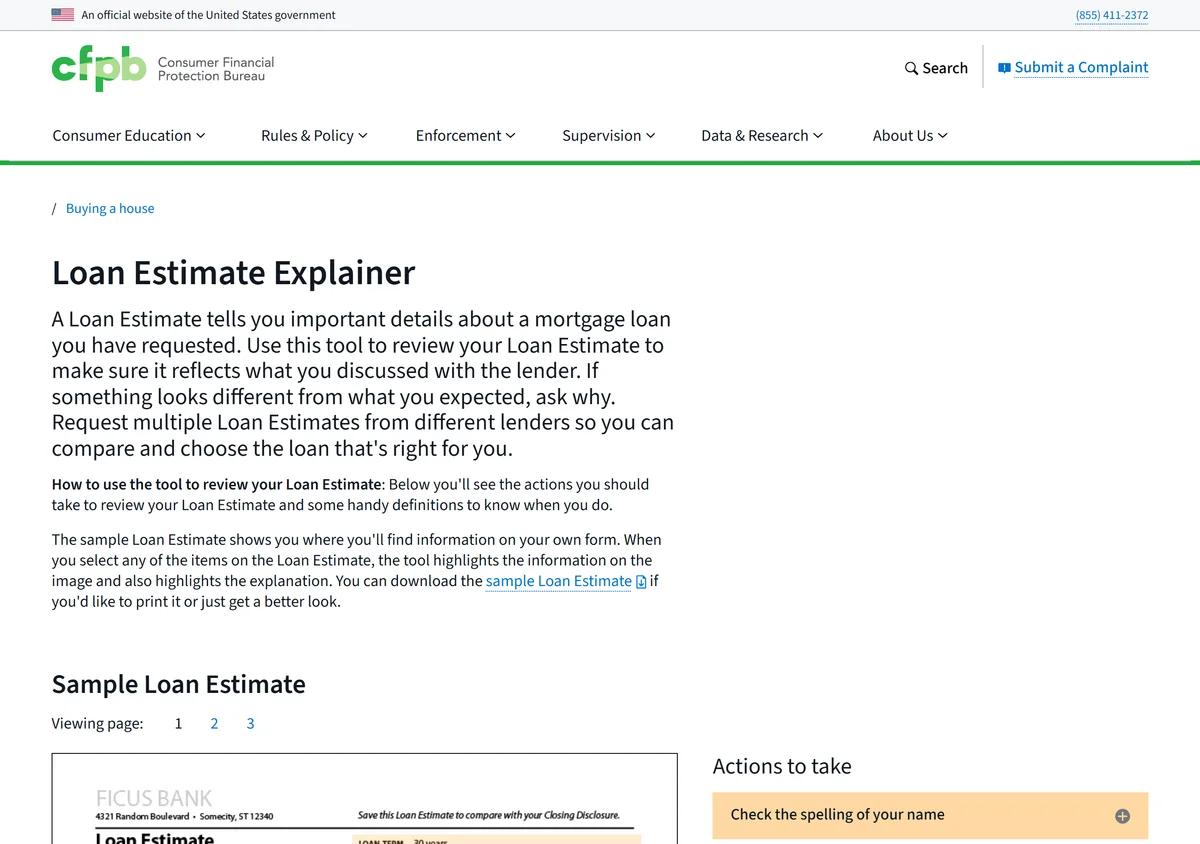
When you compare Loan Estimates, compare the same loan type, term and down payment. Look at the rate, any points, the lender credits and the cash to close. Because I am a broker, I do this comparison across multiple lenders for you, and I show you the options I would not pick too, so you can see why. To test a price and down payment yourself, use my mortgage payment calculator. Its illustration uses FHA at 1.75% upfront and 0.55% a year in MIP and conventional mortgage insurance at about 0.5% a year under 20% down; your real numbers come from your file.
How do Texas property taxes and the homestead exemption change the payment?
Texas has no state income tax, so property taxes do the work. Many DFW cities run about 2% of the home's value a year or more. On a lot of first homes, the tax is the biggest line after principal and interest. That is why I use the real rate for the address you are looking at, not a statewide average. Two homes at the same price in neighboring cities can have different payments.
Most first-time buyers pay taxes and insurance through an escrow account, so they are part of the monthly payment. On a fixed-rate loan your principal and interest never change, but the total payment can move when the tax bill or insurance premium changes.
After you move in, file your homestead exemption with your county appraisal district: Dallas, Tarrant, Collin, Denton or whichever county your home is in. It lowers the taxable value for school taxes. You file once after you move in. Veterans with a VA disability rating can get partial exemptions, and veterans rated 100% can be fully exempt on their home. My Dallas–Fort Worth city guide covers how this plays out across the metroplex.
How long does it take from preapproval to keys?
Preapproval can be quick once your documents are in. House hunting takes as long as it takes. From an accepted offer, most loans close in about 21 to 30 days. Some of my recent clients closed a purchase in 9 days when the file was ready, but every file is different. My guide on how fast you can close on a house in Dallas explains what speeds it up.
After the contract is signed:
- Option period and inspection. Your agent tracks the contract dates. The inspection tells you about the home's condition; the appraisal is separate and is for the lender.
- Underwriting. Send requested documents quickly. Do not open new credit, move large sums or change jobs without calling me first.
- Closing Disclosure. You get it at least three business days before closing. We compare it with your Loan Estimate line by line.
- Closing day. Sign at the title company, the loan funds, and you get the keys. Always confirm wire instructions by calling the title company at a number you already know.
New construction in Frisco, McKinney or Celina has its own rhythm. Builders often offer incentives through their in-house lender. It is worth comparing that offer with an outside one before you sign.
Who can explain the mortgage process and help a first-time buyer?
Whether you are asking who helps in Grapevine, who to talk to in Denton or who can explain the mortgage process near Plano, the honest answer is: someone who will pick up the phone and work your file from start to finish. That is how I work.
- I am a broker, not a bank. At Edge Home Finance I shop your loan with multiple lenders instead of fitting you into one bank's menu. A no from one lender is often not the final answer.
- One person from first call to closing. You talk to me by phone, text or email. No call center and no hand-offs.
- A weekly update to you and your agent until the file is clear to close, and I keep the title company in the loop.
- Every option compared, including the ones I do not recommend, plus a real 3 to 5 year plan for the home, not just a rate.
- A Navy veteran and Naval Academy graduate who started out closing loans for first-time buyers, teachers and veterans.
A few real files: in Dallas, a buyer came to me already preapproved elsewhere for a second look, and we restructured the deal into a better one. In Fort Worth, a builder's in-house lender could not read a buyer's active-duty and reservist pay; we could, and the buyer got full builder concessions and about $25,000 in equity on day one. In Kansas City, buyers who were told they would not qualify closed on a renovated home in 15 days. You can see all of them on my recent closings page.
My clients have given me 5.0 stars across 24 reviews. Risee S., a first-time buyer, wrote: "My questions, my uncertainties, were all answered right away." You can read more about Craig and how I work, or book a 15-minute call and ask me directly.
Questions buyers ask Craig
Is it hard to buy a first house in Celina or other new-build suburbs?
What credit score does a first-time buyer need?
Can I buy a home in DFW with no money down?
Can family give me money for the down payment?
Do I need a real estate agent before I talk to a lender?
When do I file the Texas homestead exemption?
I was already preapproved somewhere else. Can you take a second look?
Does a first call cost anything or hit my credit?
Educational information, not a loan offer or commitment to lend. Programs, rates and guidelines change and depend on the lender and your full file; ask Craig for current terms. Craig Scott NMLS #2650008, Edge Home Finance LLC NMLS #891464. Equal Housing Opportunity.