Mortgage preapproval in Dallas–Fort Worth: what it takes and when your letter is strong enough to offer
Prequalification is a quick estimate. Preapproval means your income, assets and credit have been verified, and that is the letter sellers in Dallas–Fort Worth take seriously. My online application takes about ten minutes, and once your documents are in, most buyers have a letter quickly, often the same day. Get it before you tour homes. If another lender capped your price or said no, ask a broker for a second look.
Key takeaways
- Prequalification is an estimate. Preapproval is a reviewed file: income, assets and credit are checked before the letter goes out.
- The application takes about ten minutes. With your documents in, a letter often comes the same day.
- Get preapproved before you tour, and before you pick an agent if you like. Relocating buyers can do it before they arrive in DFW.
- An online letter is enough to offer only if someone actually reviewed your documents. Ask what was verified.
- A low price cap or a no from one lender is not the final answer. As a broker I can take the same file to a different lender.
Is prequalification the same as preapproval in Plano?
No, and the difference decides how much a seller trusts your offer. Prequalification is a quick estimate built on what you tell a lender: roughly what you earn, what you owe, what you have saved. Nobody checks it. It is useful when you are still deciding whether to buy this year.
Preapproval verifies your income, assets and credit. When I preapprove you, I look at the pay stubs, the statements and the credit report before the letter goes out, so your offer is not built on a guess. That is why I recommend preapproval, not prequalification, before you tour a single home.
Plano shows why it matters. Corporate moves around Legacy come with tight timelines: a few days to see homes, then back to the old city. A solid preapproval before you tour means the homes you see are homes you can actually buy, and you can write an offer the same weekend.
What the table shows
| Stage | What is checked | What it is good for |
|---|---|---|
| Prequalification | Nothing is verified; it uses the numbers you give | A rough price range before you start looking |
| Preapproval | Income, assets and credit reviewed against your documents | Touring with confidence and making an offer sellers take seriously |
| Preapproval for a specific home | Your letter checked against the address, price, taxes and insurance | Confirming the payment and the letter amount before you sign an offer |
| Final approval (clear to close) | The full file plus the property: appraisal, title, remaining conditions | Closing day; most loans get here in about 21–30 days |
How to read it: each stage adds a check. A seller cares about the second row and up. If your letter came from the first row, it will not carry much weight in a competitive DFW offer.
What papers do I need for a home loan in Allen?
The list is shorter than most people expect. Lenders want to see three things: how you are paid, where the down payment and closing money comes from, and what you already owe. The credit report covers most of the third part. Whether you are buying in Allen, Richardson or Arlington, the list is the same; what changes is how your income is built.
What the table shows
| Document | Who usually needs it | Why it matters |
|---|---|---|
| Recent pay stubs | Anyone paid by an employer | Shows your current pay and year-to-date earnings |
| W-2s from the last two years | Employees | Shows your income is steady over time |
| Tax returns | Self-employed buyers, and anyone with commission, rental or side income | Shows the income a lender is allowed to count after expenses |
| Bank and investment statements | Everyone | Proves the down payment and closing money and where it came from |
| Gift letter | Buyers using money from family | Shows the money is a gift, not a loan you must repay |
| Certificate of Eligibility | VA buyers | Confirms your VA benefit; I can pull it for you in most cases with basic service information |
| Signed employment contract | Physicians starting a new role | Some physician programs let you close before your first paycheck |
How to read it: start with the first row that fits you and work down. Your exact list depends on your income and the loan program; I send you the precise list after the application so you are not guessing.
Two tips save the most time. First, send full statements, every page, even the blank ones. Second, if a large deposit shows up that is not your paycheck, keep the record of where it came from. If you own a business, my self-employed mortgage guide for DFW walks through tax returns and how lenders read them. Veterans can see how the benefit works on my VA loans page.
How long does preapproval take in Lewisville?
The application takes about ten minutes. Once your documents are in, most buyers have their preapproval quickly, often the same day. The part that slows things down is almost always a missing document, not the review.
- Start the application. Open my secure online application and create an account with your name, email and a password. You will see my name as your mortgage advisor, so you know the file comes straight to me.
- Upload your documents. Use the table above. If you changed jobs, are moving money between accounts or plan to sell a home first, tell me now.
- I review and compare. I check your income, assets and credit, compare lenders and programs, and send you a preapproval you can shop with, along with the payment it assumes.
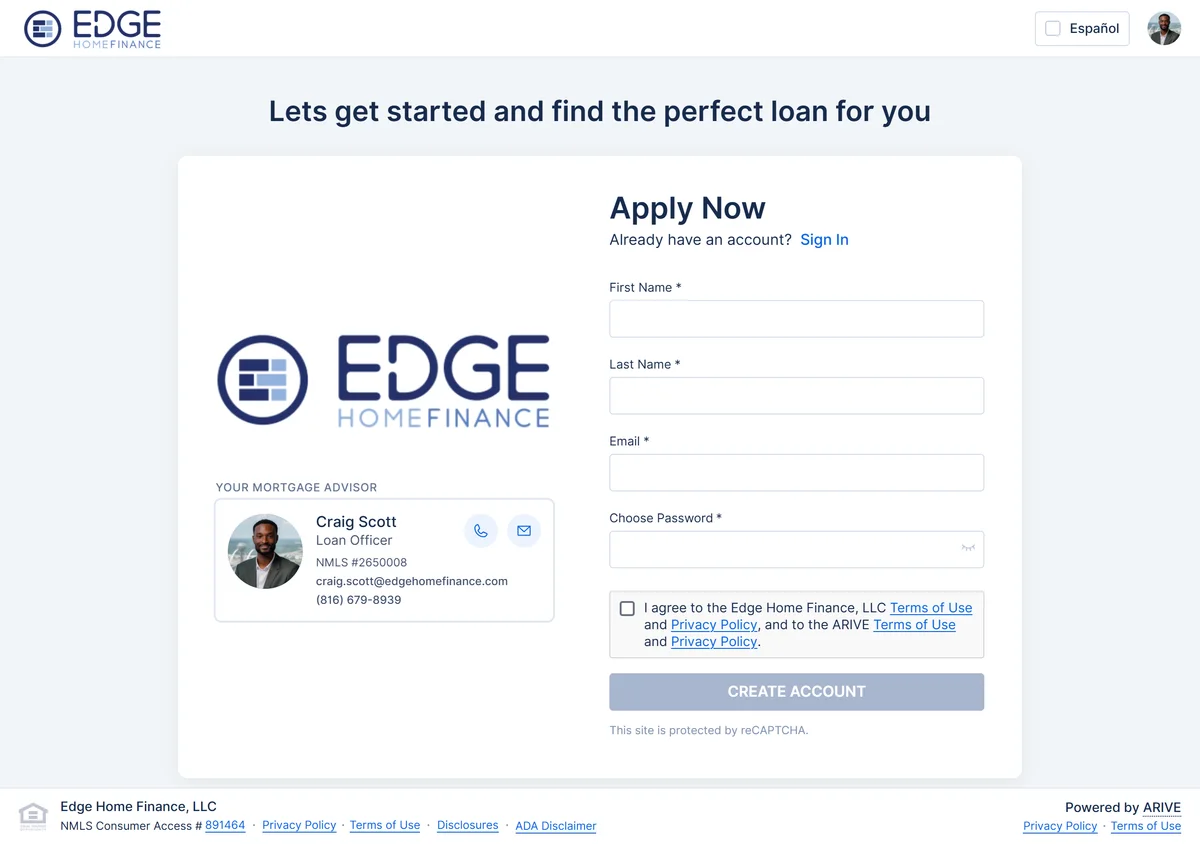
If you have a Lewisville showing on Saturday, tell me that when you apply. I will tell you what is still missing and whether we can finish in time. Keep in mind the preapproval clock and the closing clock are different: preapproval often takes a day, while most loans close in about 21–30 days. My guide on how fast you can close on a house in Dallas explains what speeds that up.
Can I get preapproved before I choose a Realtor in Frisco?
Yes. You do not need an agent, a house or a contract to get preapproved. I recommend doing it before you tour, and many buyers do it before they choose an agent. You walk into that first agent meeting with a real number, and the agent can focus your search instead of guessing.
Frisco is a good example. It is one of the fastest-growing cities in the country, with a lot of new construction to compare. Builder sales offices will ask who your lender is on the first visit. Arriving preapproved lets you compare the builder's lender with an outside offer on equal terms, which I also suggest in McKinney's new subdivisions.
Before you shop, decide two numbers: the monthly payment you are comfortable with, and the cash you want left in savings after closing. You may qualify for more than either number. That is fine; your budget is your call, not the lender's.
If you are moving to Dallas–Fort Worth from another state, I can preapprove you before you arrive so you can make offers right away. A lot of my clients relocate, including military families on PCS orders. You can see what I say about each part of the metroplex on my Dallas–Fort Worth cities page, and buying for the first time is covered step by step in my first-time home buyer guide.
Not sure whether to start now or in three months? Fifteen minutes on the phone, no credit pull, and you will know.
Book 15 minutes with CraigIs an online preapproval enough to make an offer in Colleyville?
It can be. What matters is not whether you applied online, but whether anyone reviewed your documents before the letter was issued. My application is online too; the difference is that I check income, assets and credit before the letter goes out.
Some websites hand out a letter seconds after you type in estimates. That letter is really a prequalification with a nicer header. If a listing agent in Colleyville or Southlake calls the lender to ask what was verified, the answer needs to be everything that matters.
Four questions to ask before you send the letter with an offer
- What was verified? Income, assets and credit should all be yes.
- Is the letter current? Lenders set their own expiration. If your job, debts or savings changed since the review, ask for an updated letter.
- Does it fit this house? Send your loan officer the address, price and down payment. Texas has no state income tax, so property taxes do the work: many DFW cities run about 2% of value a year or more. I use the real rate for the address, plus insurance and any HOA dues.
- What is still open? Every preapproval has conditions, such as the appraisal and title. Know which ones remain so nothing surprises you after the contract.
To test a few prices before you call, use my mortgage payment calculator. It is an illustration, not a quote, but it shows quickly how taxes and insurance change the monthly number.
Who can review my preapproval for a Fort Worth house?
Any licensed loan officer can, and a broker is well placed to do it, because I can take the same file to several lenders instead of one bank's menu. Send me your current letter, the Loan Estimate if you have one, and the address if you have found a home. Then tell me what bothers you: a price cap that is too low, a payment that looks high, or a flat no.
Second opinions are a big part of my work. A buyer in Dallas came to me already preapproved elsewhere and wanted another look. We restructured the deal and got him a better one, and it was a smooth close on his VA purchase. In Fort Worth, a builder's in-house lender could not read a buyer's active-duty and reservist pay. We could, secured the full builder concessions, and closed in just over 3 weeks with $25,000 in equity on day one.
Realtor partner Craig Houston put it this way in his review: “My client was working with a previous lender who could only qualify him to a certain purchase price. Craig was able to land him with a lender who could break through that barrier.” Lenders read income, credit and program rules differently. A cap from one of them is not a cap from all of them.
How to compare two offers fairly
Use the same price, down payment and loan type for both, then compare the Loan Estimates line by line: rate, monthly payment, lender charges, credits and cash to close. By federal rule, a lender must give you a Loan Estimate within 3 business days of receiving your application, and the CFPB encourages buyers to request more than one and compare them.
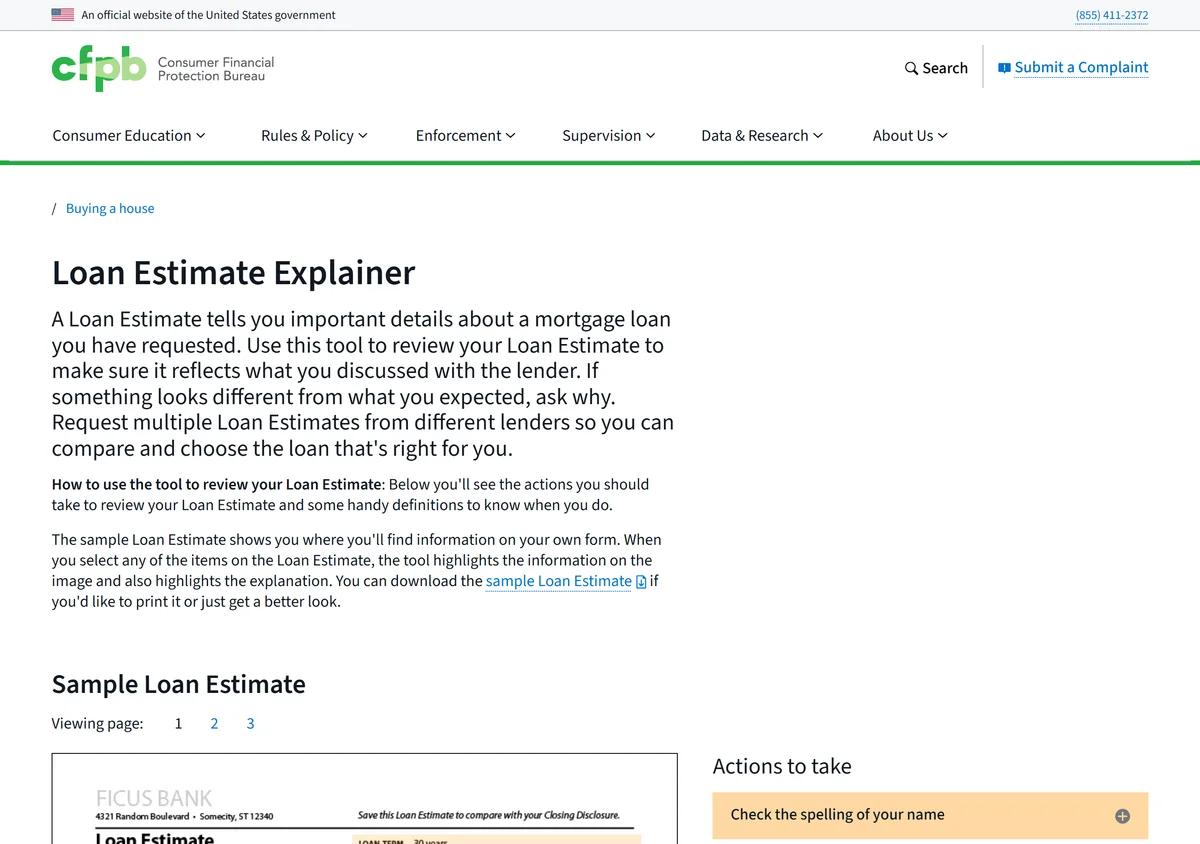
One worry stops people from asking: will a second credit check hurt my score? Most credit scoring models treat several mortgage inquiries within a short shopping period as one, so comparing lenders within a few weeks is normal and expected. If you are already under contract, share your deadlines with me first, and I will tell you whether switching fits the timeline before you change anything. You can read more of these stories on my recent closings page.
Can a mortgage broker preapprove me in Southlake?
Yes. A mortgage broker issues preapprovals just like a bank does. The difference is what happens behind the letter. A bank can only offer its own programs. As a broker at Edge Home Finance, I shop your loan with multiple lenders and match the file to the one that fits it.
That matters most when your file is not ordinary. In Southlake and Colleyville, a higher price may call for jumbo loans, where pricing varies a lot between lenders. Doctors and residents may fit physician loans with little or no down payment. Buyers rebuilding credit may do better with FHA loans at 3.5% down, and some homes on the edges of the metroplex qualify for USDA loans with zero down. Many lenders look for a 620 credit score or higher, but because I work with multiple lenders, a no from one bank is often not the final answer.
You can compare all loan options before we talk, or let me run the two or three that fit you side by side, including the ones I do not recommend, so you can see why.
How do I keep my preapproval strong until closing?
A preapproval is a snapshot of your finances on the day it was reviewed. The lender checks again before closing, so keep the picture the same.
- Do not open new credit. No new car loan, store card or furniture financing until after closing.
- Tell me before you change jobs or pay structure. A move from salary to commission can change what a lender counts.
- Leave the down payment money where it is. Moving it between accounts creates paperwork you will have to explain.
- Keep paying every bill on time. One late payment can move a score.
- Keep your documents handy. If the search runs long, the lender will ask for fresh pay stubs and statements.
None of this means you cannot live your life. It means call me first, and I will tell you whether something affects the loan.
Why get preapproved with Craig
I am Craig Scott, a Navy veteran, a Naval Academy graduate and a mortgage broker at Edge Home Finance (my NMLS is #2650008). Here is what that means for your preapproval:
- Preapprovals that hold. Income, assets and credit are reviewed before the letter goes out, so your agent can stand behind your offer.
- Many lenders, one point of contact. You talk to me from the first call to the closing table, not a call center.
- Weekly updates to you and your agent until the file is clear to close. More on how I work with agents is on my page for Realtor partners.
- A second look when someone says no. Builder's lender said no? Price capped too low? Send it over.
- Proof, not promises. 5.0 stars from 24 reviews, and recent closings in Dallas, Fort Worth, Sachse and Aledo. Every file is different and results are not guaranteed, but the stories are real.
When you are ready, book a 15-minute call or apply online in about ten minutes. If another lender already gave you a letter, have it handy. You can read more about me and how I work.
Questions buyers ask Craig
Does getting preapproved hurt my credit score?
Is my first call with Craig a credit pull?
How long is a preapproval letter good for?
Can I get preapproved while I still live in another state?
Do I have to use the lender that preapproved me?
Can I get preapproved if a builder's lender turned me down?
What credit score do I need for preapproval?
Educational information, not a loan offer or commitment to lend. Programs, rates and guidelines change and depend on the lender and your full file; ask Craig for current terms. Craig Scott NMLS #2650008, Edge Home Finance LLC NMLS #891464. Equal Housing Opportunity.