How Fast Can You Close on a House in Dallas–Fort Worth?
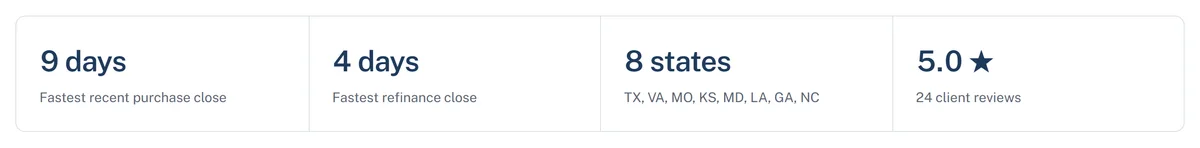
Most home loans I close in Dallas–Fort Worth take about 21 to 30 days from contract to keys. When the file is ready, it can go faster: my fastest recent purchase closed in 9 days and my fastest refinance in 4 days. Every file is different and no one can guarantee a date, but a complete application, an early appraisal and quick answers to the underwriter are what make 21 days or less possible.
Key takeaways
- Plan on about 21–30 days; many of my files close in 21 days or less.
- Two federal waiting periods are fixed: the Loan Estimate within 3 business days of your application, the Closing Disclosure at least 3 business days before closing.
- Most delays come from missing documents, the appraisal, title issues or new debt during the loan.
- You can apply online in about ten minutes, so a pre-approval before a weekend offer is realistic when your documents are ready.
- I send you, your agent and title a weekly update, and I pick up the night before closing.
How long does it take to close on a house in DFW?
The honest range is about 21 to 30 days for most purchase loans. That is what I tell every buyer on our first call, whether they are looking at a starter home in Mesquite or a new build in Prosper.
Faster is possible. A purchase I closed in Houston came together in 9 days on a tight timeline, and a refinance in Sachse closed in 9 days and saves the homeowner over $1,000 a month. My fastest refinance closed in 4 days. Those files moved fast because everything was ready when it was needed, not because anyone skipped a step.
So when someone asks me, "Can you close in 21 days on a Mesquite home?" my answer is: very often, yes, if we start clean. I will tell you on day one what could stretch it, so nobody is surprised a week before your move.
What are the stages from application to keys?
Every mortgage goes through the same stops. Knowing them helps you see where time is spent and where you can save it.
- Application. You apply online in about ten minutes. I review your income, assets and credit and compare lenders and programs for your file.
- Pre-approval. Once your documents are in, I issue a letter you can shop with. Mine are reviewed before they go out, so your offer is not built on a guess.
- Loan Estimate. Once you have a contract and a full application, the lender must send your Loan Estimate within 3 business days. It shows your rate, payment and closing costs.
- Appraisal. The lender orders an appraisal of the home. On a VA loan the appraiser also checks VA minimum property requirements.
- Underwriting. The underwriter verifies everything and may send conditions: a letter of explanation, an updated bank statement, a missing page.
- Clear to close. All conditions are met and the loan is approved for closing.
- Closing Disclosure. You must receive it at least 3 business days before closing. It lists your final terms and cash to close.
- Closing. You sign with the title company, the loan funds and you get your keys.
What does a fast closing timeline look like, stage by stage?
Here is how the stages line up and what keeps each one short. The fixed rules come from federal disclosure law; the rest depends on your file.
What the table shows
| Stage | Timing | What keeps it fast |
|---|---|---|
| Online application | About 10 minutes to submit | Have pay stubs, W-2s or tax returns and bank statements ready to upload |
| Pre-approval letter | Quickly, once documents are in | Send every page of every statement the first time |
| Loan Estimate | Within 3 business days of the application (federal rule) | Review it the day it arrives and tell me you want to proceed |
| Appraisal | Varies with appraiser schedules and the property | Order it early; give access to the home right away |
| Underwriting and conditions | Varies by lender and by file | Answer conditions the same day; no new debt or job changes |
| Clear to close | After all conditions are met | Title work and insurance ordered early, so nothing waits at the end |
| Closing Disclosure | At least 3 business days before closing (federal rule) | Sign it as soon as you receive it and check the numbers against your Loan Estimate |
| Closing and funding | The whole loan: about 21–30 days for most files | Wire funds verified with title by phone; IDs ready |
How to read it: the two rows marked as federal rules cannot be shortened, so a fast closing comes from the rows that depend on you, the lender and the appraiser. The more of the right-hand column you do early, the closer you get to 21 days or less.
What slows a closing down?
In my experience, slow files are rarely about the lender being lazy. They come from a short list of things:
- Missing or partial documents. A bank statement with a missing page or an unsigned tax return means a new condition and another round with the underwriter.
- Large deposits nobody can explain. Money that shows up in your account needs a paper trail. Gift funds need a gift letter.
- The appraisal. A busy appraiser, a value that comes in low or a repair the lender requires can add days. On VA loans I handle minimum property requirements, Tidewater notices and reconsiderations as part of the process.
- Title issues. An old lien, a survey question or a probate detail has to be cleared by the title company.
- Changes during the loan. A new car loan, a new credit card balance or a job change can force the underwriter to re-review your file.
- A late change after the Closing Disclosure. Certain changes, such as a different loan product, an added prepayment penalty or an APR that is no longer accurate, start a new 3-business-day waiting period.
- The wrong lender for the file. One of my Fort Worth buyers was buying a new build, and the builder's in-house lender could not read the buyer's active-duty and reservist pay. We could, and the loan closed in just over 3 weeks with full builder concessions.
What can you do to close in 21 days or less?
This is the part you control. Buyers who close fast do these things:
- Get pre-approved before you tour. Not pre-qualified: pre-approved, with income, assets and credit reviewed. My mortgage pre-approval guide for DFW lists every document.
- Upload everything at once. All pages of the last statements, pay stubs, W-2s or tax returns. If you work for yourself, start earlier; my self-employed mortgage guide explains what lenders ask for.
- Pick the loan early. VA loans, FHA loans and a conventional 30-year fixed mortgage each have their own appraisal and paperwork rules. Deciding on day one saves a re-start later.
- Answer conditions the same day. When the underwriter asks for something, a same-day answer can save days.
- Freeze your credit life. No new loans, cards or big purchases until after closing.
- Line up insurance and title early. Get your homeowners insurance quote as soon as you are under contract.
- Sign the Closing Disclosure the day it arrives. The 3-business-day clock starts when you receive it.
Under contract or about to be? Fifteen minutes on the phone tells you how fast your file can realistically close.
Book 15 minutes with CraigCan I get pre-approved before a weekend offer?
Often, yes. If you found a home in Grand Prairie or Garland on a Thursday and want to put in an offer ASAP, here is the fastest path:
- Apply online. It takes about ten minutes.
- Upload your documents right away. The pre-approval comes once income, assets and credit are reviewed, and that review is what makes the letter hold up when a seller compares offers.
- Call or text me so I know you are racing a deadline.
I will not promise a time before I see your documents, because a letter that falls apart in underwriting costs you more than a day's wait. What I can tell you is that once the documents are in, most buyers have their pre-approval quickly. In Plano, where corporate moves around Legacy mean tight timelines, I tell buyers to get this done before they tour, not after.
How fast have recent closings actually been?
These are real loans from my recent closings, with the timeline each one shared publicly.
What the table shows
| Where | Loan | Timeline | What made it work |
|---|---|---|---|
| Sachse, TX | Refinance | Closed in 9 days | Saves over $1,000 a month |
| Houston, TX | VA purchase | Closed in 9 days | Tight timeline, no-cost temporary buydown |
| Brownsville, TX | VA refinance | Under 2 weeks | Entitlement restored, rate lowered, $0 out of pocket |
| Norfolk, VA | VA purchase | 2 weeks from contract | Zero down, no PMI |
| Kansas City, KS | Purchase | Closed in 15 days | Told they would not qualify; closed early to fit their schedule |
| Norfolk, VA | VA purchase | Under 3 weeks | Bought while deployed at sea |
| Kansas City, MO | VA mixed-use | Closed in 21 days | Home and business in one closing, seller paid closing costs |
| Fort Worth, TX | VA purchase | Just over 3 weeks | Moved away from a builder's lender that could not read military pay |
| Kansas City, MO | 1% down purchase | Funded 10 days before closing | Retired school teacher, 1% down |
How to read it: most of these land between about 2 and 3 weeks, and the fastest ones were refinances or files that were ready on day one. Every file is different, and none of these is a guarantee for yours.
Buyers say the same in their reviews. Dominique P. wrote, "We closed the house in 9 days, seamlessly." Newjean S. wrote that everything moved smoothly and "we were fully prepared to close in just 3 weeks."
Is closing on a new build in Frisco, McKinney or Prosper different?
The loan stages are the same, but the closing date usually follows the builder, not the lender. In Frisco and McKinney, where there is a lot of new construction and builder incentives, I recommend comparing the builder's lender with an outside offer before you lock in. A builder's lender is not always faster or cheaper, and sometimes it simply cannot approve the file.
If you are building from the ground up with a VA benefit, the VA one-time close construction loan works on a different clock: one closing covers the land, the build and the permanent loan, with no payments for up to 11 months while the home is built with participating lenders.
Who answers when you need a mortgage person on a tight deadline?
A tight deadline in McKinney or Rockwall is not the time to sit in a call center queue. With me you get one person from the first call to the closing table:
- Weekly updates to you, your agent and the title company until the file is clear to close.
- A phone that gets answered. Call, text or email me. I am the person who picks up when you call, the night before closing included.
- A 15-minute call to start. Book a time and I will call or text you to set it up. No credit pull.
Agents send me files that need a fast close or a second look; you can see how I work with them on my page for Realtor partners.
Why work with me when the clock is ticking?
I am a mortgage broker at Edge Home Finance, so I can shop your loan with multiple lenders instead of fitting you into one bank's menu. When one lender's timeline or guidelines do not fit your contract date, I can take the file to one that does.
I am also a Navy veteran and a Naval Academy graduate who has used my own VA loan more than once, in more than one state. I know what it is like to buy on orders with a fixed move-in date. You can read more about me and how I work.
My clients give me 5.0 stars across 24 reviews, and my recent closings span 8 states. Here in Dallas–Fort Worth I work across Dallas, Tarrant, Collin, Denton and Parker counties; see the DFW cities I serve. If you are buying your first home, start with my first-time home buyer guide, then compare all loan options or run a payment with the mortgage calculator.
Ready to see how fast your file can close? Apply online in about ten minutes, call me or book 15 minutes.
Questions buyers ask Craig
Can a lender close in 21 days on a home in Mesquite or Garland?
What is the fastest a mortgage can close?
Can I close faster on a refinance than a purchase?
Why do I have to wait 3 days after the Closing Disclosure?
Does a weekend or holiday change my closing date?
Does a VA loan take longer to close?
Can I get pre-approved over a weekend?
Will you keep my agent updated?
Educational information, not a loan offer or commitment to lend. Programs, rates and guidelines change and depend on the lender and your full file; ask Craig for current terms. Craig Scott NMLS #2650008, Edge Home Finance LLC NMLS #891464. Equal Housing Opportunity.